Tech Drags Market as Investors Brace For Nvidia
Published as of: November 16, 2026, 9:14 a.m. ET
Listen to this article
Listen here or subscribe to the Schwab Market Update in your favorite podcast app.
| The markets | Last price | Change | % change |
|---|---|---|---|
| S&P 500® Index | 7,561.67 | -30.73 | -0.40% |
| Dow Jones Industrial Average® | 52,347.55 | +50.46 | +0.10% |
| Nasdaq Composite® | 25,136.27 | -229.82 | -0.91% |
| 10-year Treasury yield | 5.14% | -0.01 | -- |
| U.S. Dollar Index | 103.51 | +0.09 | +0.09% |
| Cboe Volatility Index® | 20.62 | +1.33 | +6.89% |
| Gold | $3,871.10 | -$14.80 | -0.38% |
| WTI Crude Oil | $87.53 | -$1.02 | -1.12% |
| Bitcoin | $64,370 | -$4,590 | -6.67% |
(Monday market open) Wall Street has an early case of butterflies approaching Nvidia's (NVDA) earnings tomorrow afternoon. Volatility jumped and risk-off sentiment dominated. Today spotlights Federal Reserve Chairman Kevin Warsh, who makes opening comments at a noon ET conference, one of 10 Fed speakers this week.
Even without Nvidia, it would be a busy stretch. October retail sales, Walt Disney (DIS) and Home Depot (HD) results all arrive tomorrow, with a Nike (NKE) investor meeting thrown in. Anthropic likely dominates news later this week with its expected initial public offering (IPO). In the meantime, bitcoin suffered dramatic early losses Monday to three-month lows, and crude oil and yields retreated.
Major indexes fell Friday on profit taking, but the Nasdaq had its best week since August. "What stands out most in the face of this week's reckoning for Nvidia is the resilience of the broader market," said Alexandra Semenova, financial insights strategist at the Schwab Center for Financial Research (SCFR), writing Friday. "Investors haven't broadly rushed out of risk. Instead, they're finding opportunities elsewhere, both within the AI ecosystem and across other parts of the market."
To get the Schwab Market Update in your inbox every morning, subscribe on Schwab.com.
Three things to watch
- Industry impact assessed as Nvidia results loom: Nvidia is at the center of a vast network of AI chip agreements that some criticized as "circular financing"—meaning companies loaning other companies money to buy their products. It's also invested billions in other companies. The AI buildout's success hinges in part on Nvidia's ability to continue supplying quality chips on time and continue innovating. Those are question marks with Jensen Huang gone. "Huang's departure leaves a lot of questions about the future of Nvidia, and I don't see how it can be interpreted other than a negative for the AI secular growth story," said Nathan Peterson, director of derivatives research and strategy at SCFR. Nvidia has 80% market share in advanced AI chips and appears well positioned into 2027, analysts said. Still, future business could be at risk on worries about potential fallout, and any possible guidance change would draw sharp focus. Concerns about talent loss also surround the earnings call tomorrow hosted by CFO and interim CEO Colette Kress. Questions could touch on the CEO search and looming congressional hearings. Earnings per share and revenue are seen up about 90% annually.
- Consumer stocks and inflation: Expected rate hikes would normally be kryptonite for staples and other rate-sensitive stocks, possibly threatening rotation out of tech. Instead, many consumer names show resilience. Both staples and discretionary are up 2.6% over the last five sessions. This could suggest investors see pricing power after robust economic data. The share of firms expecting to raise prices over the next three months jumped to 37% in the most recent National Federation of Independent Businesses (NFIB) report, up from 31% a month earlier and the highest since July 2022. Expectations are for no change in headline October retail sales and a 0.4% monthly rise excluding autos. Holiday spending so far this year is tracking above the last two years, Bank of America said. The worry is whether the wealth effect might wane as stocks struggle and rates rise. Chances of a rate hike next month are 91% for a 25-basis point rise and 9% for a 50-basis point increase, according to the CME FedWatch Tool. "The base case is two additional hikes this cycle, and I see risk to the upside of more hikes rather than fewer," said Collin Martin, head of fixed income research and strategy at SCFR.
- Busy week on the "home" front: Housing data kicks off tomorrow with the National Association of Home Builders Housing Market Index, a measure of builder sentiment. October pending home sales are out Wednesday, after September's reading hit its lowest level since records began in 2001. Building permits and housing starts are also due Wednesday, though both have been steady since post-COVID heights in 2022. "It's a very difficult time to buy [a home] right now with mortgage rates where they are," Martin said on the latest episode of the On Investing podcast. "But if you're locked in at a low rate, and you have no plans of moving or selling your house anytime soon, the rise in borrowing costs might not bother you." Martin added that this contrast puts the Fed in a tough spot: "Parts of the economy just aren't very rate sensitive right now."
On the move
- Chip and AI-related stocks followed Nvidia lower before the open, with sharp losses for CoreWeave (CRWV), Nebius (NBIS), Lumentum (LITE), Sandisk (SNDK), and SK Hynix (SKHY). All fell 5% or more, with pain increasing after Bloomberg reported that the U.S. has moved to limit remote access to advanced AI chips. The rule will require licenses to reexport advanced AI chips to Brazil, Singapore, Indonesia, Malaysia, and Thailand.
- Crypto-related companies were among the hardest hit in Monday's early action as bitcoin futures dropped almost 7%. Risk-off trading and ideas that U.S. interest rates could rise ganged up on cryptocurrencies, Bloomberg reported. Shares of Strategy (MSTR) plunged 8%, with Circle Internet Group (CRCL) also down almost 8% and Coinbase (COIN) off 7.4%.
- Intel (INTC) dropped 5% early, with other chip firms. It also received news of a lawsuit by shareholders accusing the company of "concealing" information about slowing sales, Reuters reported. Shares fell 29% in one day last month after Intel reported weak results due to slowing PC sales.
- Humana (HUM) rose 2% early on an upgrade to outperform from RBC Capital, which cited earnings potential.
- Cogent Communications (CCOI) slid 5% after getting downgraded by Wells Fargo to underweight from equal weight. Third-quarter results missed estimates.
- USA Rare Earth (USAR) dropped more than 5% after getting downgraded to market perform from outperform at William Blair, which cited challenges including feedstock shortages.
- Home Depot (HD) slipped ahead of tomorrow morning's earnings. Last time out, in August, Home Depot executives described the housing market as "frozen," and said customers hadn't shown much zest for large projects.
- U.S. Treasury yields fell slightly early today after soft economic data Monday from both China and Japan.
- Advanced Micro Devices (AMD) and Broadcom (AVGO) plunged 9% and 5%, respectively, Friday, after earlier gains of 30% and 24% on ideas they could gain share from Nvidia.
- Apple (AAPL) rose again Friday and hit an all-time high on reports of solid iPhone demand and as investors seek perceived defensive plays in tech less tied to AI turbulence and spending.
- Meta Platforms (META) climbed 2% Friday as The Wall Street Journal reported the company is testing a prediction market application.
More insights from Schwab
Historic lessons from CEO successions: Huang's departure from Nvidia last week is one of many times CEOs unexpectedly left a company, but it's unusual that Nvidia didn't have a succession plan. Schwab's new analysis discusses how to check for one before investing and looks at how previous prominent CEO changes affected companies.
The pitfalls of rivalry: The latest episode of Choiceology with Katy Milkman explores what happens when we compare ourselves to our peers in highly competitive, ranked environments—and how social comparisons can distort both our performance and our happiness.
Opening and funding a crypto account at Schwab: Our new video takes investors through the process of buying and selling crypto directly, which requires opening and funding a crypto account linked to an existing Schwab brokerage account.
Prioritizing for weddings and beyond: Parents planning to help their child celebrate the big day might want to extend their gift beyond the wedding itself. Our new financial planning article explores ways to help adult children understand balancing wedding spending with longer-term priorities.
Chart of the day
Data source: Nasdaq. Chart source: thinkorswim® platform.
Past performance is no guarantee of future results.
For illustrative purposes only.
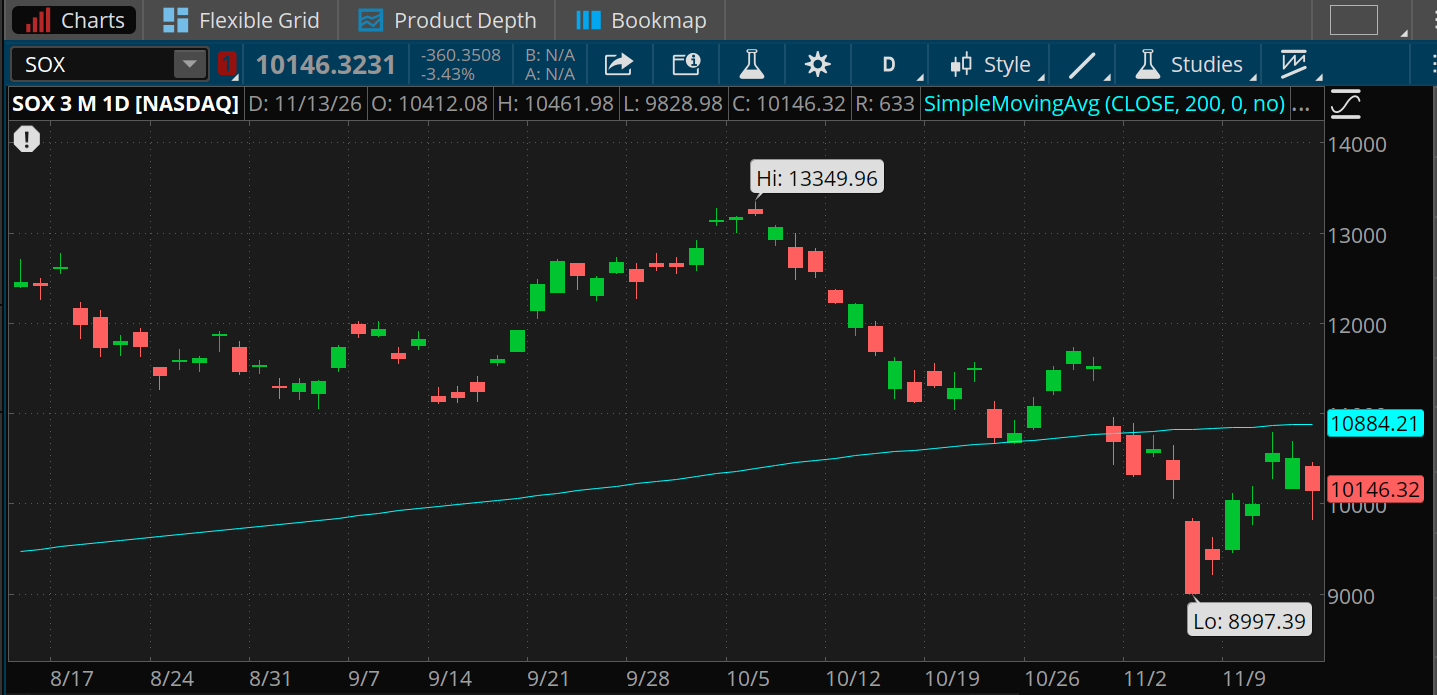
Despite profit taking and pressure from Nvidia on Friday, the PHLX Semiconductor Index (SOX—candlesticks) climbed 8% last week. It's still below its 200-day moving average (blue line), however, and well below October's peak. Last week's rebound appears to be a technical response to oversold conditions. However, the SOX appears to have run into resistance at its 200-day SMA in what could be a bearish pullback.
The week ahead
Monday, November 16: Expected morning earnings from Baidu (BIDU) and Tyson Foods (TSN).
Tuesday, November 17: October retail sales, October industrial production and capacity utilization, and expected morning earnings from Home Depot (HD) and Walt Disney (DIS). Expected afternoon earnings from Nvidia (NVDA).
Wednesday, November 18: October housing starts and building permits, FOMC minutes, and expected morning earnings from TJX (TJX), PDD Holdings (PDD), Lowe's (LOW), Target (TGT), and Williams-Sonoma (WSM). Expected afternoon earnings from Palo Alto Networks (PANW).
Thursday, November 19: Leading Economic Indicators for October from Conference Board, and expected morning earnings from Walmart (WMT), Alibaba (BABA), and NetEase (NTES). Expected afternoon earnings from Intuit (INTU), Ross Stores (ROST), and Gap (GAP).
Friday, November 20: University of Michigan final November Consumer Sentiment and expected morning earnings from BJ's Wholesale Club (BJ).
Monday, November 23: Expected afternoon earnings from Hewlett Packard Enterprise (HPE) and Zoom Communications (ZM).